Calculate one Minneapolis delivery month against another without losing the contract-year mapping or units. This guide keeps the exchange, dated legs and historical-data boundary visible so the quoted relationship can be checked.
Define the side of each leg
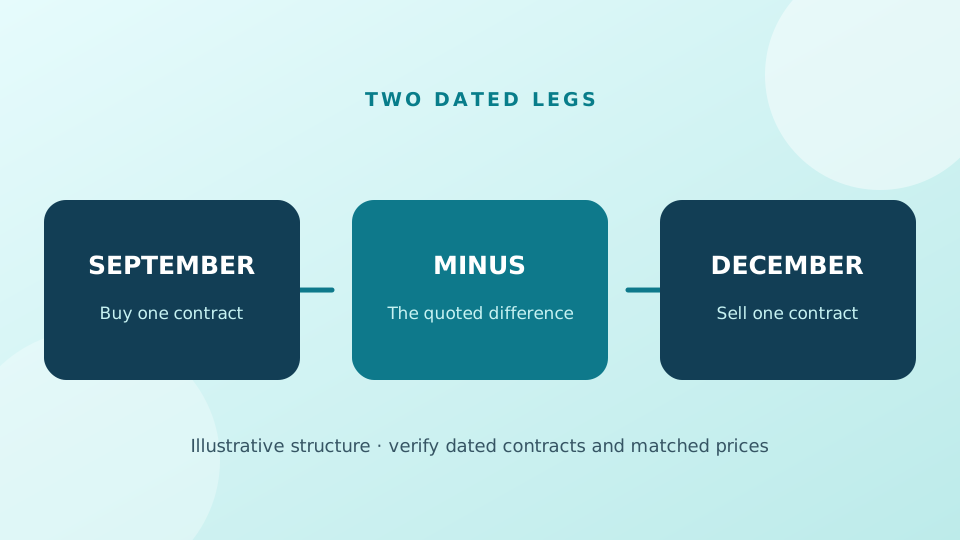
For a long calendar spread in this research system, buy the first listed month and sell the second. The quoted structure is first price minus second price, in cents per bushel. Reversing the position reverses the change in value. Write the formula next to the chart so a rising line is not confused with a rising outright wheat price.
If September is 620.75 cents and December is 639.00 cents on the same date, September minus December is −18.25 cents. This is a worked historical observation from 30 June 2025, not a current market price. A one-cent change in this one-to-one spread is $50 before fees because each contract covers 5,000 bushels.
Date matching is non-negotiable
Both prices must represent the same trading day. Missing values are not zero, and carrying yesterday’s price forward would create a synthetic quote that no trader could have observed. A reliable history retains only dates where both dated legs exist and reports how many dates survive the join.
When a spread crosses December into a new year, map historical seasons by relative year. December 2026 versus March 2027 must be compared with December 2020 versus March 2021, not December 2020 versus March 2020.
Interpret a change, not just the level
If the long spread moves from −18.25 to −8.25 cents, it gained 10 cents or $500 for one spread before costs; the two outright prices may both have risen or both have fallen. A negative spread level is not automatically a losing trade. The entry and exit difference, position direction, execution costs and interim drawdown determine the hypothetical result.
Historical comparisons need the same calendar window, the same leg mapping and a report of excluded years. The blue historical line in a research chart can be useful for pattern recognition, but backtest P&L must use each season’s actual raw spread values.
See the dated contracts behind the formula
Explore matched historical Minneapolis prices, individual years and the selected date window. The dataset has no verified current MGE spread.
Open MGE Historical Research →Primary sources
Exchange and USDA sources establish product definitions and context. Recheck the current rules and dates before using a contract.
Continue this series
Educational historical research, not investment advice. Futures and multi-leg spreads involve substantial loss, execution and delivery risk. Historical results do not guarantee future outcomes. Imported Minneapolis prices stop on 24 October 2025; current quotes and margin must be verified independently.